Business insurance for California contractors, property owners and small businesses
Tell us what you do and what you need covered. A licensed agent in our Glendale office will call you back with a quote.
- Prefer to talk? Call 818-351-2304.
- Open Monday to Friday 9 am to 5:30 pm, Saturday and Sunday 9 am to 3 pm.
- Farmers Insurance agency. California license 0C47385.
- Hablamos español.
Who we cover
Contractors
General liability, workers' comp and commercial auto for licensed trades. When a general contractor or client asks for a certificate of insurance before you start, we issue it.
- Plumbing
- Electrical
- HVAC
- Roofing
- Landscaping and tree service
- Pool service
- Painting
- Janitorial
- Handyman
- General contractors
Property owners
Coverage for the building, liability for what happens on the property, and directors and officers coverage for association boards.
- HOAs and condo associations
- Apartment buildings
- Rental houses and duplexes
- Commercial buildings
Small businesses
A business owners policy combines liability and property coverage in one policy. Add workers' comp when you hire, and commercial auto when you put a vehicle to work.
- Shops and offices
- Service businesses
- Businesses with employees
- Businesses with vehicles
What each coverage does
Most businesses need two or three of these. We'll tell you which ones apply to you and which you can skip.
- General liability
- Pays when your work or your premises injures someone or damages their property, and covers your legal defense. It's the policy behind most certificates of insurance that clients and general contractors ask for.
- Workers' compensation
- Pays medical bills and lost wages when an employee is hurt on the job. California requires it for every employer with at least one employee, and for some contractor trades even with none.
- Commercial property
- Covers the building you own, plus tools, equipment, inventory and furnishings, against fire, theft and other covered losses. Landlords can add coverage for rent lost during repairs.
- Commercial auto
- Covers trucks, vans and cars used for work, and the employees who drive them. Personal auto policies often exclude or limit business use.
- Business owners policy
- General liability and commercial property in one policy, usually with business income coverage, for small and mid-sized businesses. It normally costs less than buying them separately.
- HOA and condo association
- Property coverage for common areas, general liability, directors and officers liability, and a fidelity bond, set at the limits California's Davis-Stirling Act calls for.
A local agency you can call
Nunez Insurance Agency is a Farmers Insurance agency on East Colorado Street in Glendale. You work with an agent who knows your account, in English or Spanish.
We're open seven days a week, and you can reach us by phone, text or email.
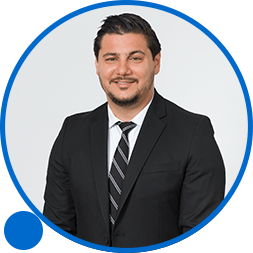 Alex Anthony NunezFounder and CEO
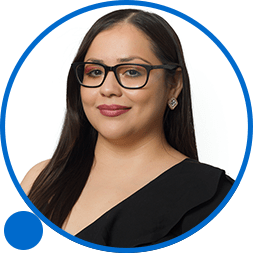 Wendy TrejoBusiness insurance specialist
I signed up with Farmers through Susie. From start to finish, Susie is a 5 Star Agent. She is very responsive to any questions or concerns I have and she is great at figuring out what policies fit best for your family status and income, giving you the best policies that you can afford.
So far I have had a great experience. I had a great agent help me, Susi was very helpful and informative. I appreciate all the help and the great insurance quote I was given.
Questions we hear most
What insurance does a California contractor need to keep a license?
The Contractors State License Board requires a $25,000 contractor bond and either a workers' compensation policy or a signed exemption if you have no employees. Roofing (C-39), concrete (C-8), HVAC (C-20), asbestos abatement (C-22) and tree service (D-49) licensees must carry workers' comp even with no employees. Contractors licensed as an LLC must also carry liability insurance of at least $1 million.
Is general liability insurance required for contractors in California?
The state requires it only for contractors licensed as an LLC. In practice most general contractors, property managers and commercial clients ask for a certificate of insurance before you start work, often with a $1 million per occurrence limit.
Do I need workers' comp if I only have one employee?
Yes. California requires every employer with one or more employees to carry workers' compensation, including part-time employees. Owners with no employees are usually exempt, except in the contractor trades the license board names.
Does my personal auto policy cover a work truck?
Usually not fully. Personal auto policies often exclude or limit vehicles used mainly for business, vehicles titled to a business, and employees driving them. A commercial auto policy covers those uses and offers higher liability limits.
What insurance does an HOA need in California?
An association typically carries property coverage on the common areas, general liability, directors and officers liability, and a fidelity bond. Under the Davis-Stirling Act, owners are shielded from personal liability for common-area claims when the association carries at least $2 million in general liability (100 or fewer separate interests) or $3 million (more than 100). Volunteer directors get similar protection when the association carries at least $500,000 in directors and officers coverage, or $1 million if the development is not exclusively residential.
What does apartment building insurance cover?
It covers the building itself, your liability if a tenant or visitor is hurt on the property, and usually the rent you lose while a covered loss is being repaired. It does not cover tenants' belongings. Tenants need their own renters policy for that.
What is a business owners policy?
A business owners policy, or BOP, combines general liability and commercial property coverage in one policy, and usually includes business income coverage. It is designed for small and mid-sized businesses and normally costs less than buying the coverages separately. It does not include workers' comp or commercial auto.
What do you need from me to prepare a quote?
For a business: the business name, what you do, how long you have been operating, estimated annual revenue and payroll, and any claims in the last few years. For a property: the address, year built, number of units and any updates to the roof, plumbing or electrical. If you have a current policy, the declarations page speeds things up.
Get your quote started
Send the form and an agent will call you during office hours. Or call us now.
818-351-23041447 E Colorado St #D, Glendale, CA 91205
Monday to Friday 9 am to 5:30 pm, Saturday and Sunday 9 am to 3 pm